

Cash Advance: Get 250 Fast
4.7

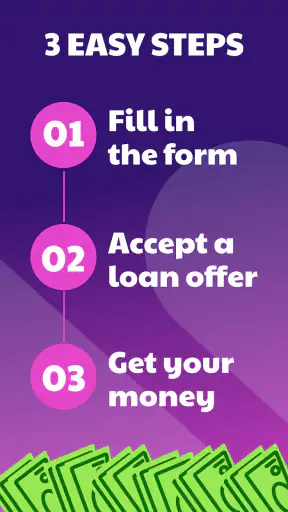
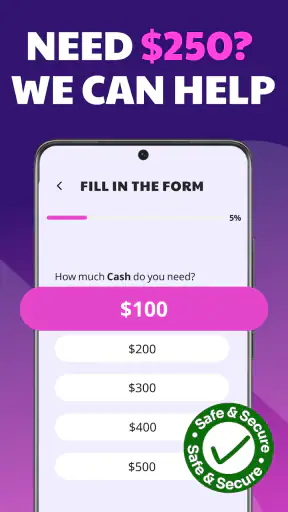
When an unexpected bill lands between paydays, the hardest part is often not the amount itself but the timing. Cash Advance: Get 250 is designed around that narrow problem: giving users a simple way to explore a payday loan or cash advance through a finance app rather than searching through several services. I found its appeal easy to understand, especially for someone who needs a short-term option and wants a straightforward starting point instead of a complicated budgeting platform.
My overall impression is cautious but positive. The app is free to install, aimed at Everyone, and published by KOMPANIIA LORENS PP. It has built a sizeable audience, with over 100 thousand installs and a 4.7 average from around 25 thousand ratings. Those figures suggest that the basic experience works for many people, but they should not be mistaken for a guarantee that every user will qualify for an advance or find the resulting terms suitable.
What the app is really useful for
A focused route to short-term borrowing
The central capability is its focus on cash advances and payday loans. That focus matters because it keeps the app’s purpose clear. I would not open it expecting a full bank account, a long-term savings tool, investment tracking, or a detailed debt-management system. Its role is much narrower: help a person begin the process of looking for fast access to money.
That narrow purpose is also the app’s strongest practical advantage. Traditional alternatives can involve visiting a bank, calling a lender, filling out several separate forms, or comparing results across unrelated websites. A dedicated mobile starting point can feel less intimidating when the immediate question is simply, “What options might be available to me before payday?”
Still, the phrase “cash advance” should be treated as a description of the borrowing category, not as a promise of instant money. An app can simplify the first steps, but approval, eligibility, repayment obligations, and the final cost remain important parts of the decision. I would use this app to investigate an option, not to assume that money is guaranteed the moment I open it.
Why the no-subscription approach matters
One detail I appreciate is that the app is presented without subscription fees. That changes how I would approach it. A subscription-based finance app can create pressure to keep paying simply for access to a service, while this model is more suitable for someone who wants to inspect a short-term borrowing route only when a need arises.
Free access does not mean borrowing is free. That distinction is especially important here. The app itself may cost nothing to download, while any loan or advance connected with the process can have its own repayment terms and charges. Before accepting anything, I would read the total repayment amount, the due date, and every fee shown in the offer rather than judging the option by the requested amount alone.
The “250” promise needs a careful reading
The app name highlights 250, which gives users a quick idea of the intended borrowing scale. I see that as useful for setting expectations: this is positioned around a relatively small, short-term cash need rather than a major personal loan. That makes it more relevant to an urgent utility payment, a transport problem, or a necessary purchase than to a large medical, housing, or education expense.
At the same time, I would not interpret the number in the name as an automatic approval amount. A responsible user should treat it as the app’s advertised focus and then examine the actual offer presented during the process. The amount available to one person may depend on eligibility and other conditions, so the sensible workflow is to check the details before planning a repayment around them.
How I would use it in practice
I would begin by installing the app only when I had a specific reason to investigate a short-term advance. The first useful habit is to decide the exact amount needed before opening the application. If I need money for a particular bill, I would write down that bill, its due date, and the date when I expect income. This prevents the common mistake of borrowing a rounded amount simply because it is offered.
From there, I would follow the app’s steps carefully and treat every screen as part of a financial decision, not just a form to rush through. I would check whether the requested amount matches the real need, review the repayment timing, and pause whenever wording is unclear. The app’s simple design goal is helpful, but simplicity should never replace reading the conditions.
Before submitting sensitive details, I would also make sure I was using the official app-store version and that the developer name displayed for the application matched KOMPANIIA LORENS PP. That small verification step is worthwhile for any finance app. A familiar-looking icon is not enough protection when personal and financial information may be involved.
A realistic payday scenario
Imagine I have a necessary car repair due on a Monday, but my salary arrives later in the week. I could open Cash Advance: Get 250 to see whether a short-term option is available, compare the repayment obligation with the amount arriving on payday, and decide whether the timing genuinely works. In that situation, the app’s value is not merely speed. It is the ability to bring the borrowing decision into one focused workflow while the problem is still clearly defined.
The decision becomes less attractive if the repair is only the first of several expenses. If I already expect another bill before my next income arrives, taking an advance may move the pressure rather than solve it. I would use the app only when I could identify a realistic repayment source and still cover food, housing, transport, and other essentials afterward.
Small workflow habits that make a difference
One useful technique is to compare the repayment date with the date money is actually available, not merely the date income is expected. A weekend, bank delay, or payroll change can make a short gap longer than planned. I would leave room for that uncertainty instead of assuming the earliest possible arrival.
A second technique is to capture the important terms for my own records before agreeing. I would note the amount requested, the amount to repay, the due date, and any stated charges. This makes it easier to check the repayment later and prevents the details from becoming vague after the application is finished.
A third is to use the app as a comparison starting point rather than stopping at the first available result. If my bank offers an overdraft, a credit union provides a small loan, or a bill provider allows a payment arrangement, those alternatives may be cheaper or less disruptive. The convenient route is not automatically the best financial route.
Where it differs from ordinary alternatives
A bank’s overdraft or personal-loan service may be more suitable when I already have an established relationship, predictable income, and enough time for a conventional review. A credit union may offer a more personal lending process, although joining or applying can take additional effort. A credit card can provide flexibility, but interest and fees can become expensive when a balance is carried.
Compared with those options, this app is most appealing when the immediate need is small and the user wants a dedicated mobile entry point. Its convenience is also its main risk: a short route to an application can make borrowing feel easier than the repayment really is. I would therefore compare the complete cost and timing, not just the speed or the amount shown in the app’s name.
The friction I would expect
The app’s simplicity may not answer every question a cautious borrower has. A person who wants extensive financial education, detailed spending analysis, or long-term debt planning will probably find a banking app or budgeting tool more useful. Cash Advance: Get 250 is built around a specific transaction path, so it should not be judged as though it were a complete personal-finance dashboard.
There is also an emotional friction that no interface can remove. When money is tight, users may focus on receiving funds and skim the repayment information. I think this is the biggest practical weakness of any payday-loan-oriented experience, including this one. The app can make the process clearer, but it cannot make an unaffordable repayment affordable.
Another limitation is that the app’s usefulness depends on the offer and the user’s circumstances. A person may complete the initial steps and still decide that the terms do not fit. That is not necessarily a failure; in fact, stopping before accepting unsuitable borrowing is a good outcome. I would rather see the app as a way to reach an informed decision than as a tool whose success is measured only by obtaining money.
Who will get the most from it
I think the best match is someone facing a defined, temporary cash gap, who understands when repayment will be possible and who is willing to compare alternatives. The app can also suit users who prefer handling an initial finance application on a phone instead of navigating several separate lender websites.
It is less appropriate for someone who needs recurring help with everyday expenses. If each payday already disappears before essential bills are covered, another advance can deepen the cycle. In that situation, a conversation with a bank, credit counselor, community service, or trusted financial adviser is likely to be more useful than repeatedly seeking short-term credit.
I would also steer away from it for a large, long-term expense. The app’s cash-advance focus does not make it a substitute for a structured personal loan, emergency fund, insurance claim, or negotiated payment plan. Matching the tool to the problem is crucial: a small timing issue may fit, while a persistent financial shortfall needs a broader solution.
Basic suitability and device details
The application is free and carries an Everyone content rating, which makes it broadly accessible from an app-store perspective. It runs on Android devices using version 7.0 or later. On the software side, the current release is 1.2.2, so I would keep the installation updated through the normal store process rather than relying on an old copy.
Those technical details make it approachable for people using older compatible Android phones, but compatibility should not be confused with financial suitability. The more important question is whether the repayment plan fits the user’s income. A phone that can run the app is only the first requirement; a realistic budget is the one that determines whether using it is sensible.
My recommendation after weighing the trade-offs
Cash Advance: Get 250 is a focused finance app with a clear use case. I like that it avoids subscription fees and concentrates on helping users explore a short-term cash advance instead of pretending to be an all-purpose money manager. Its strong user response and broad install base make it worth considering as a starting point, especially when a small, temporary gap has a clear repayment plan.
My recommendation comes with a firm condition: read the complete repayment terms before accepting any advance. I would compare the total cost with an overdraft, credit union product, bank option, or payment arrangement, and I would walk away if the due date would leave essential expenses uncovered. The app can make the search more convenient, but the responsibility for the final borrowing decision remains with me.
For that reason, I would recommend Cash Advance: Get 250 to a careful user who needs a focused way to investigate short-term borrowing and already knows how repayment will work. I would not recommend it as a routine income supplement or as a replacement for longer-term financial support. Used selectively, it can reduce the effort involved in exploring an urgent option; used impulsively, its convenience could make a difficult money problem harder.
4.7
984.00 Reviews
Pros
- Simple application process with minimal information required
- Clear repayment details help users understand the borrowing terms
- May provide quick access to funds during short-term emergencies
- Convenient mobile access without visiting a bank or lender
- Useful loan comparison tools can help review available options
Cons
- Approval and funding are not guaranteed for every applicant
- Fees and interest may make short-term borrowing expensive
- Repayment deadlines can be difficult for users with limited income
- Availability and terms may vary by state or personal eligibility
- The app may connect users with third-party lenders and services


